
The best gap is rarely empty; it is usually badly served.
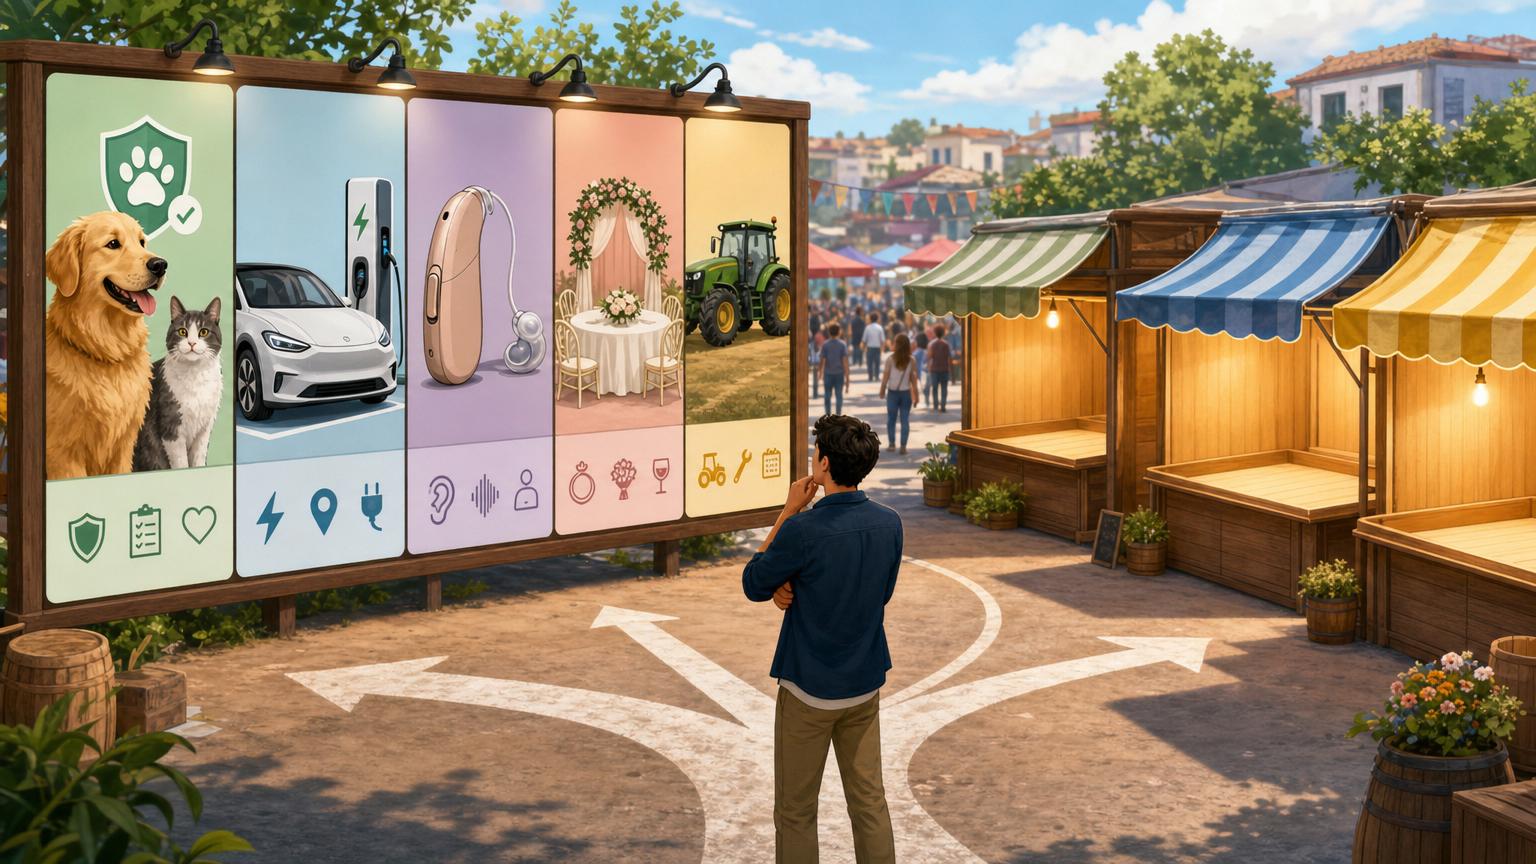
A founder staring at niche lists usually sees two bad options: blood-red markets packed with funded brands, or tiny corners so obscure they barely have buyers. The useful middle ground is less obvious. A niche becomes attractive when the existing players are present but lazy—thin content, outdated prices, weak filtering, poor mobile UX, or no real trust signals.
That is why niche choice is not a hunt for zero competition. It is a three-way tradeoff: how hard rankings and customer acquisition will be, whether reliable pricing data can actually be collected and refreshed, and whether commissions or lead-gen payouts are strong enough to support the work. A market with rivals can still be open if incumbents are weak at data quality, comparison depth, or conversion design.
- Best targets often have fragmented suppliers, changing prices, and low-quality incumbent pages.
- A niche with moderate competition can outperform an empty one if data access and payouts are stronger.
What “still open” actually means
A niche is still open when buyers face unresolved pricing friction even in a crowded market.
Fragmented suppliers, inconsistent fees, poor filtering, and stale listings create room for a sharper product. Competition matters less than whether the market is still inefficient.
Commercial intent and decision complexity usually matter more than raw traffic.
The strongest categories have users close to purchase, multiple variables to compare, and prices that change often enough to justify checking. Smaller, high-intent demand can monetize far better than broad curiosity.
A viable niche also needs normalizable data, healthy unit economics, defensibility, and manageable compliance.
Messy attributes, thin payouts, instant copycats, or heavy regulation can erase the advantage of having data. The best openings balance data access with sustainable margins and tolerable legal overhead.
The recommended niches earn their place only when they pass all of the following tests. A strong score in one area does not rescue a weak score in another.
Searches signal active shopping, not casual research. Buyers have enough variables, urgency, or confusion that side-by-side comparison clearly reduces effort and risk.
Prices, fees, availability, and key attributes can be gathered and standardized with acceptable refresh costs. The category tolerates imperfect feeds better than it punishes stale or misleading data.
Customer acquisition can be paid back through commissions, leads, or repeat visits. The model retains an edge through brand, workflow, or proprietary cleanup while staying inside manageable regulatory boundaries.
A niche is only “open” when all three align: demand, workable data, and economics that survive compliance.
Markets worth rejecting early
Some categories look irresistible and still punish new entrants. Flights, hotels, broad electronics, and insurance are frequent dead ends: incumbents dominate branded search, own supplier relationships, and benefit from trust that took years to build.
Other markets fail on unit economics or dependency:
- Tiny basket sizes leave too little commission to fund acquisition.
- Single-source feeds create API hostage risk if terms, coverage, or uptime change.
- Commodity catalogs invite price wars with no defensible angle.
A final disqualifier is intent mismatch. If shoppers really want curation, alerts, or hand-picked bargains, the stronger model may be a deal-focused site rather than a pure comparison engine.
Two or three brands capture most demand
One upstream feed controls core data
Commission cannot support acquisition
Buyers want discovery more than side-by-side comparison
Where buyers still need help
The strongest openings are rarely glamorous. They tend to be repeat purchases or monthly bills where pricing changes often, plans are hard to normalize, and small differences compound into meaningful savings.
Broadband
Broadband remains promising because headline speed is only part of the decision. Real comparison requires separating intro pricing, contract length, router fees, installation charges, price rises after month 12, and address-level availability.
Underserved pockets still exist:
- Rural and edge-of-network households comparing fixed wireless, satellite, and legacy DSL
- Renters and students who care more about no-contract terms than peak speed
- Home workers and gamers who need latency, upload speed, and outage history, not just Mbps
Traveler eSIMs and mobile plans
This market looks crowded until the real use cases are examined. Travelers struggle to compare regional coverage, throttling rules, hotspot allowances, activation friction, number retention, and fair-use caps hidden behind simple “10 GB / 30 days” packaging.
The gap is widest for people crossing borders frequently, mixing work and leisure, or needing a second line only briefly. A useful comparison layer can map plans to trip pattern, not just data allowance.
EV charging and time-of-use tariffs
EV economics are still messy. The cheapest option depends on vehicle efficiency, home charging access, local utility tariff windows, public charging markups, subscription fees, and driving schedule.
That complexity creates room for tools built around specific situations: apartment dwellers without driveways, multi-EV households, or drivers choosing between flat-rate electricity and time-of-use plans. Here, the winner is often the site that turns tariff logic into a simple monthly cost model.
Local services are still open
National directories may look busy, but local services effectively restart in every metro. Supply is fragmented, pricing is inconsistent, and availability shifts by neighborhood, timing, and inventory mix. The real edge comes from turning those messy limits into searchable filters, which is why site structure matters so much.
Broad directories usually stop at names, ratings, and a quote button. Local comparison wins when it captures the constraints that actually decide the purchase:
- Self-storage: climate control, drive-up access, elevator vs ground floor, teaser-rate expiry, truck clearance, insurance requirements.
- Coworking: hot desk vs dedicated desk, 24/7 access, meeting-room credits, team suite availability, commute fit.
- Airport parking: shuttle frequency, walking distance, height limits, cancellation cutoff, covered spots, overnight security.
- Moving services: crew size, stairs or elevator fees, COI availability, travel charges, fragile-item handling, narrow booking windows.
That level of detail is hard to centralize nationally, but very workable one city at a time. A focused entrant can normalize terms, verify live constraints, and surface the cheapest usable option rather than the lowest headline price. For buyers, that feels far more trustworthy than a generic directory.
B2B and prosumer buyers are often the better opening
For many founders, business and prosumer categories are a cleaner entry point than broad consumer markets. The audience is smaller, but the buying intent is usually far stronger: a team replacing software, a contractor pricing tools, or a creator choosing a paid workflow stack is already close to a decision. That often supports better monetization through qualified leads, booked demos, annual subscriptions, or higher-value affiliate payouts.
Just as important, pricing pain is usually worse. Consumer products may have visible sticker prices; B2B products hide real cost behind seat tiers, usage caps, onboarding fees, support plans, and contract discounts. Many incumbents still publish thin “best X software” pages that compare features, not total cost.
Where the gap is real
The best openings tend to share a few traits:
- Opaque pricing: seats, overages, setup fees, and minimum contracts
- Role-specific needs: agency vs in-house team, solo pro vs small company
- Meaningful switching cost: migration, training, integrations, compliance
- Repeatable math: cost per user, per location, per project, or per transaction
That creates room for tools that feel genuinely useful:
- Calculators estimating monthly and annual spend by team size or usage
- Scenario comparisons such as “5-person agency” versus “50-seat support team”
- Pricing models that separate base fees, add-ons, implementation, and likely overages
In these markets, a practical cost model often beats a longer review.
How to tell if a niche is buildable
-
Read the SERP, not just the keyword
Check what already wins the page: marketplaces, Google modules, programmatic directories, forums, or calculators. If the result page already resolves the buying choice, a new comparison layer starts at a disadvantage.
-
Count true merchant depth
A niche needs enough distinct sellers after removing white-label brands, franchise duplicates, and reseller clones. Twenty logos can shrink to five real price setters surprisingly fast.
-
Test price extraction early
Pull sample prices from a few dozen merchants across devices and locations. If pricing sits behind ZIP gates, JavaScript, logins, or quote flows, the tech stack needs to fit that extraction pain.
-
Model refresh pressure
Match expected margin to update frequency. A category that changes hourly demands very different crawling, QA, and anomaly detection than one updated monthly or seasonally.
-
Confirm partner tolerance
Some merchants like leads but dislike transparency, scraping, or brand-term bidding. The model gets brittle when revenue depends on suppliers that can revoke access at the first disagreement.
Hidden fees, messy bundles, and manual normalization create support work that scales faster than traffic.
Regulated sectors can add disclosure, licensing, audit, and archival duties that wipe out thin commissions.
A sturdy niche stays accurate during merchant churn, broken pages, and policy changes—not only during the first data pull.
- Start narrow Pick one use case, city, or customer segment rather than an all-purpose marketplace.
- Use 4/5 rule Proceed only if intent, data consistency, refresh burden, merchant depth, and payout potential each score at least 4/5.
- Best first wedges The best first wedges are regional self-storage, travel eSIMs by trip profile, and EV tariffs for home chargers.
- Expand second Once the first wedge converts, expand into adjacent plans, nearby cities, or calculator-led scenarios.
Pick the wedge, then prove it
If a niche passes the filter, the first version should behave less like a giant portal and more like a sharp tool: one audience, one comparison table, one calculator, and one update workflow. That is the cleanest bridge from research to execution, and it follows the same discipline outlined in building a price comparison site.
The safer expansion path is adjacency, not sprawl: storage by metro before nationwide, eSIMs by trip type before global plans, EV tariffs before full home-energy switching.
19 responses to “Best Niches for Price Comparison Sites Still Open to New Entrants”
The 4/5 viability score idea sounds clean, but I kinda wanted to see the weighting.
For example, if a niche has amazing payout strength and strong buyer intent, but extraction difficulty is awful and update burden is constant, do you automatically kill it? Or can economics overpower the operational pain if the market is good enough?
The “reject markets early” section was refreshing lol. So many posts basically say EVERY category is an opportunity if you try hard enough 😂
Do you have a rule of thumb for when feed dependence is too risky? Like if 80% of the useful data comes from merchant feeds, is that already a red flag, or does it depend more on whether users can verify the info themselves?
Broadband definitely fits the “buyers still need help” bucket. I’ve moved twice in the last 3 years and every provider page was basically a magic trick: teaser rates, contract terms hidden in footnotes, weird installation caveats…
My question is whether that niche is actually buildable for a new entrant if the incumbents already rank for everything obvious. Is the play to go hyper-local, or to build better filters/tools and hope Google rewards that eventually?
Broadband is hard, but not closed. I’d be cautious about attacking the broadest head terms first because incumbents are entrenched there.
The more realistic wedge is often geographic or situational: specific city availability, renter vs homeowner constraints, no-contract plans, upload-sensitive households, business-at-home setups, and so on. Better tools matter, but they usually need a narrow entry point where the query intent is underserved rather than expecting Google to reward generic usefulness on its own.
Hyper-local feels way more realistic to me. “Best internet” is a bloodbath, but “fiber options in X neighborhood/apartment type” is where people are actually desperate.
On the B2B/prosumer angle: do you think lower traffic but higher conversion still holds if the pricing is so opaque that nobody will show a real number until a sales call?
I get the logic around calculators and scenario modeling, but I’ve also seen that turn into “fake precision” where the comparison looks smart yet the final quote is miles off. Feels risky for trust.
What about categories where the “best comparison” might actually be a consultant, not a site?
That line in the article about some intent being better served by another model stood out to me. There are buying decisions where users don’t just need normalized data — they need interpretation, negotiation help, or someone to tell them what tradeoff actually matters. In those cases, is a comparison site just a lead-gen wrapper for a human service?
Not saying that’s bad, btw. Just wondering if that changes how you evaluate SERP fit and defensibility.
Yes, and I think recognizing that early saves a lot of wasted effort. Some markets look attractive because the pricing is opaque, but the real buying job involves diagnosis, implementation context, or negotiation rather than straightforward comparison.
In those cases, a content/comparison layer may still work, but usually as a qualification and education step before handing off to a person. That absolutely changes SERP fit: you’re no longer just asking “can I rank a comparison page?” but “does search intent support a hybrid model where comparison reduces confusion and a human closes the gap?”
This is basically how a lot of B2B software buying works in real life. People say they want “comparison,” then 20 minutes later they want a sane person to explain the invoice 😂
The part about “open” meaning unresolved buying friction rather than “no competitors” was probably the most useful point here.
A lot of niche site advice online still acts like finding an empty keyword space is the goal, when in reality an empty space can also mean nobody wants the thing. Curious how you’d personally separate “messy but worth solving” from “messy and impossible to monetize”?
That’s exactly the distinction I wanted to highlight. An empty SERP is not automatically an opportunity; sometimes it’s just a weak market signal.
The practical test I use is whether the friction sits close to a purchase decision and whether merchants benefit from helping resolve it. If users are comparing plans, configurations, or recurring costs right before buying, and providers have enough margin to pay for acquisition, the mess is often monetizable. If the comparison burden is huge but the payout is tiny or the buying intent is vague, it usually becomes operational pain without much upside.
Yep, this. I worked on a finance lead-gen project years ago and “hard problem” sounded exciting until we realized every extra layer of complexity killed trust instead of improving conversion.
I’m a little skeptical on travel eSIMs staying “open” for long.
The product is easier to compare than broadband or EV tariffs, and it feels like one decent brand plus strong SEO could swallow a huge chunk of that market fast. Is the opening really in comparison, or just in content + affiliate distribution before the big players consolidate it?
Fair pushback. eSIMs are definitely less structurally messy than something like home broadband, so I’d also treat them as a narrower and possibly shorter-lived opening.
Where I still think comparison can matter is plan duration, regional coverage, throttling policies, hotspot support, activation friction, and renewal behavior. Those details are often inconsistent across providers, which creates room for a better decision layer. But I agree the window may compress faster there than in heavier, regulation- or infrastructure-constrained markets.
I had the same reaction tbh. eSIM feels more like “move quickly” than “durable moat,” unless you have actual usage/testing data instead of just republishing plan tables.
Local storage / parking / moving made sense to me, but I’m wondering how ugly the ops side gets.
A comparison product sounds great until every city has different inventory rules, promo pricing, and weird availability gaps. At what point does “local fragmentation” stop being an advantage and just become a manual data-entry job with a nice landing page on top?
That’s the core tradeoff. Local fragmentation creates openings because national incumbents often smooth over important constraints, but it also pushes a lot of operational burden onto the publisher.
For me, it stops being attractive when the update burden scales faster than the value of each additional market. If you can template the data model, automate a meaningful portion of updates, and still preserve city-specific decision value, it can work. If every location behaves like a custom research project, the niche usually looks better on paper than in practice.
This is where so many “local marketplace” ideas die tbh. Everyone loves fragmentation until they have to maintain 400 slightly-different pages every week 😅
Exactly. Fragmentation is only useful if you can systematize it. Otherwise you’re building a very expensive spreadsheet business.